Joy Olivier on Covered California, PEOs, and the Insurance Mistakes That Cost You
Interview by Heather Anderson
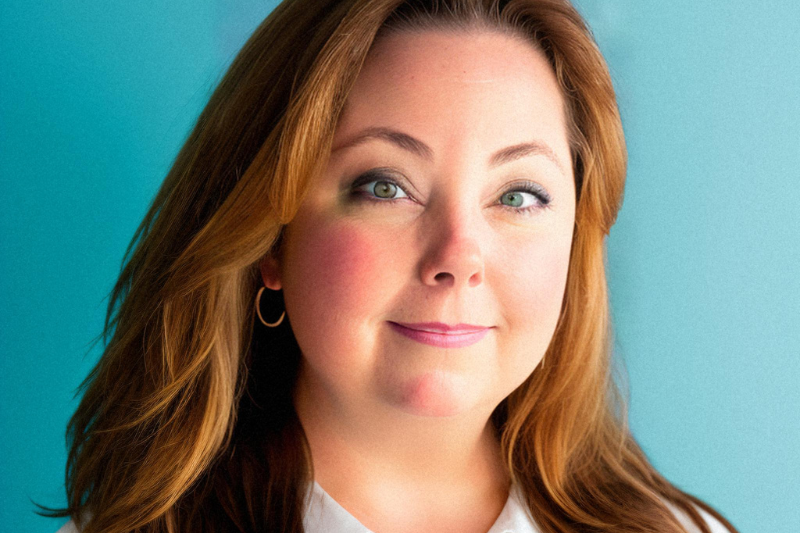
Joy Olivier has been an insurance agent for more than 20 years, and 14 years ago she pivoted her agency to specialize in Covered California so her community would have someone to call when health coverage became mandated, confusing, and easy to get wrong. Today Joy Olivier Insurance Agency represents more than 60 carriers and writes, in her words, everything but bail bonds: business, home, auto, life, health, and the benefits and retirement packages that keep small companies running. She's licensed in multiple states, comes from a family that is insurance all the way down (she married a claims adjuster), and lives on a small ranch in California with her pets and livestock. This one is less a profile and more a field guide. Keep your policies nearby.
You've been an insurance agent for over 20 years, and 14 years ago you pivoted your entire agency to specialize in Covered California. What's the biggest thing most people still get completely wrong about how insurance actually works?
I pivoted because I knew there was a need. My community was going to have to navigate mandated health care, and I wanted to be the person who could help them do it.
Fourteen years later, the biggest thing people still get wrong is accurate reporting. Most individuals do not understand what qualifies as income, why they have to update their account within 30 days of a change, and why they end up paying back tax credits when they file their taxes. That is the pain point for everyone.
The county you live in, the makeup of your household, what counts as income. All of those factors dictate the tax credits your account receives. Here's an example. Somebody reports single for the whole year, gets married in November, then files the following year as a dual-income household. They will find themselves paying most of that tax credit back. In all honesty, it would have been better to continue filing single for that year, since they were married less than half of it, and then be married on the account starting January 1. This is why it's important to have an agent who can talk through scenarios with you.
The amount of clients referred to me who open with "Covered California is a scam. They give you a low price and then you have to pay it all back with penalties." That is 100 percent inaccurate. There are no penalties with Covered California. There is reporting, and nobody explained it.
You just named about four things I've personally gotten wrong. What else trips people up?
Networks. People don't understand which providers will work with which carriers, and not every network works with every carrier. For example, Anthem does not work with John Muir in Contra Costa on the individual Covered California market. Zilch. But John Muir will work with Blue Shield. A couple of years ago, Stanford pulled out of the individual market entirely. How many people thought Covered California was the reason nobody could go to Stanford? That was a network decision. It didn't matter if you bought direct or through Covered California, nobody was going to Stanford. Having a broker to navigate that instead of spending three hours online makes a huge difference.
The other big one is people being released from Medi-Cal. It can be very daunting. You've been on a paid platform, you get a letter saying you've been released, and now you have to go back in and redo the application. Many times the Covered California application doesn't have correct data in it. People rely on it, never look at the account, and then when it's time to pick a plan or file taxes, the information was never right and they're the ones held responsible. A local agent can go into that account, review it, fill in what's missing, and make sure you're 100 percent accurate for the year ahead.
And I'll say this now, because it's honestly why I wanted to do this piece. There's a big change coming to Covered California in 2028 that most people have no idea about. I'll get to it.
Let's start with businesses. You specialize in pulling companies out of PEOs. What is a PEO, in plain English, and how do people end up paying way more than they realize?
A PEO is a professional employer organization. It's a company that helps a business manage its employee-related responsibilities through what's called co-employment. Think of it as outsourcing HR. You still hire and manage your people day to day, but the PEO handles payroll, benefits, workers' comp, HR support, compliance, and administration. Your employees become, in a real sense, the PEO's responsibility.
Here's the difference. In a PEO, you're not just paying for those services. You're paying a fee for each line, and that adds up really quickly.
The way I've built my network, I already have partners who run in the same circles I do, so we're able to give a business those same services without the fees. I typically handle all the employer-sponsored benefits and the retirement. My office handles the workers' comp. I have great payroll partners and HR administration partners who can step in. And we run together as a team, so if you ask one of us a question, we take care of it internally, just like a PEO would, and you get to focus on your business. If a company wants to explore getting out of a PEO, I've become known in the industry as the go-to.
“Everybody has too much insurance until the time of loss.”
If a mom reading this owns a business with 10 or more employees, an HVAC company, a contracting business, a medical practice, what's the single biggest insurance mistake you see owners like that make?
Not having the appropriate coverage in place. It depends on the industry, but the biggest gaps we see right now are commercial auto, EPLI (employment practices liability), and cyber, because those are the claims coming in most often.
Most of the phone calls we get from businesses are after it's too late. Something has happened, and that claim is not going to be covered. They call and say, can you help us? Do you have this coverage? No. Okay, we'll help you get it now, but that doesn't fix what already happened. Those small businesses end up paying lawyers to get untangled. We're connected with some really great attorneys for exactly that reason, but I would much rather you never need them.
One of my sayings is: everybody knows about insurance when they buy insurance, but when it's time for a claim, nobody has a clue how insurance works. So our job as a team is to make sure that when a business owner is exploring options, they are completely educated on every aspect of their liability. We actually call ourselves risk advisors, and we help owners put a plan together. Our motto is we educate, then we advocate, and then we enroll. In that order.
You've said contractors need to be careful about licensing and bonding before hiring subcontractors or vendors. What should a business owner actually ask for, and what happens if they skip that step?
Any contractor who subcontracts out should be requesting a certificate of insurance, and it should list them as an additional insured on that certificate.
Many businesses fail to do this. Then there's a claim, whether the wrongdoing was intentional or not, and the hiring business gets held responsible because it was their project. Having that certificate protects you. It means the subcontractor's policy pays out first before yours ever gets touched.
We typically ask our business owners to make sure anyone they hire as a subcontractor carries at least a million dollars in general liability. Ask for it before the work starts, not after.
Now for the solo founders and small teams, the one or two person businesses. Is it even worth talking to a broker at that size, or should they just handle it themselves?
Most agents, including me, are free to work with. So my recommendation is always to work with somebody who's licensed, who can do an insurance review and show you where the holes are, where the risk and liability may sit, so you can keep working without looking over your shoulder wondering if something bad could take away your business.
We have lots of options for the solo, two-person, three-person businesses. Just because somebody is small doesn't mean they have less liability, and it doesn't mean they have fewer options in the market.
What's something a solo founder can do to genuinely lower their insurance costs or improve their coverage that most people have no idea is even an option?
Ask whether you're looking in the right spaces. Whether it's general liability, workers' comp, or benefits, are you with a company that specializes in your industry? You may be missing opportunities because you went to a general carrier instead of one that truly understands what you do.
And if you're paying a lot, ask what's driving the cost. Have there been claims? Is your risk high because you don't have plans in place? Do you have a return-to-work plan if somebody gets injured on the job? Loss control and risk control are real levers. This is why working with an agent who can review your risk and help you put plans in place matters. You want to be paying for the insurance you'll actually use, not overpaying because you don't have a handle on your risk, and not underpaying because you're not covered correctly.
Here's the one I'm personally going to act on. If you're a solo founder or a tiny team and you need health insurance for yourself and your family, what's the move most people don't know exists?
Under the Affordable Care Act, solo owners are not eligible for employer-sponsored benefits. There are plans out there marketed to solo owners, but they aren't always ACA compliant.
So one of the recommendations we make is this. Hire a part-time admin or bookkeeper, somebody on your payroll at least 20 hours a week, and that makes your business eligible for employer-sponsored benefits. That person does not have to enroll. Maybe they have coverage through Medi-Cal, the VA, or a partner's plan. It doesn't matter. Having them on payroll still opens the door.
Now you have access to owner-only plans with carriers like United Healthcare, Blue Shield, and Kaiser, and we see fewer price increases on those plans. And here's the part people love: your premiums become tax deductible in your business. On an individual plan, you're paying post-tax. On an employer plan, you're paying pre-tax. That lowers your taxable income at the end of the year, on top of getting better coverage.
Now for moms and families. You said there's a big change coming for Covered California. What is it, and what do families need to do about it?
This open enrollment, for the 2027 plan year, is the last passive renewal period. That means if you don't touch your policy, don't update your account, don't hit confirm, you will still have your health benefits on January 1, 2027, as long as you pay your premium.
That is the last year it works like that.
Come fall of 2027, every individual or their agent must go into the Covered California account, verify all the information, and confirm. If that doesn't happen, the policy will automatically not renew, and there will be no coverage on January 1, 2028. And there is no way of reinstating it.
Our big campaign right now is getting reminders in place today, on your calendar, in your phone, wherever they'll actually get seen. Fall of 2027, touch your account. If you're working with us, we'll be touching it for you, but I want everyone in this community to know, whether you're my client or not.
If someone is filing a claim, whether it's an auto accident or a homeowner's claim, what's something people commonly say or do that ends up hurting them?
Calling the carrier before they call their agent.
Here's why. Many claims don't get paid. On homeowners, wear and tear is the big one. But the moment you call the carrier to file, even if it's not covered, it goes on your claim history as a zero-dollar payout. That can raise your rates. And when we go to shop home carriers for you, if you've had a zero-dollar water claim, most of them won't quote you for three years. You've just X'd out your ability to shop.
Water is the classic example. You come home from vacation and there's water all over the kitchen floor. What happened? Turns out the line to the ice maker was clogged and the pipe cracked. That's wear and tear. Not covered. Water claims are for sudden and accidental, like a pipe that bursts from pressure. So what we do first is fact find. If it happens on a weekend, we'll get a remediation company out there to look and clean it up, and usually right then they can tell us whether it's wear and tear or accidental. If it's accidental, excellent, we open the claim. If it's not, you haven't put a loss on your record for nothing. We'll always file if a client asks us to. That's our job. But we always give you the option to find out first.
On auto, the mistake is not gathering enough data. Get a copy of the driver's license, and if you can, a picture of the driver, because once in a while drivers swap and the person on the license isn't the person who hit you. Get the plate, get a phone number, and if anyone pulls over, get their name and number as a witness. If anybody is injured, call the police, even if the other person says please don't. You want it documented, because people are fine at the scene and have major injuries a week later. And my biggest recommendation: get a dash cam. People don't tell the truth anymore.
A lot of moms hand the insurance and financial decisions to a partner. If something changed tomorrow, divorce, a health crisis, a job loss, what would most women discover they don't actually know about their own coverage?
We work with a lot of women who are becoming aware for the first time, usually because they've left a partner. Same sex, heterosexual, doesn't matter. They come to us and they don't understand what they have or what their coverages mean.
On auto, they don't know the difference between comprehensive and collision, or whether they have rental and tow. They know what it costs and, most of the time, who the carrier is. But are they properly covered? What happens when you hit the Tesla being driven by the head surgeon at a hospital and you caused the accident? Are you sure you have the right coverage for that?
On homeowners, it's things like: is the insurance paid through an impound account or not? Who's paying it? Is it monthly? Is it endorsed? Are you even listed on the policy? That's the big eye opener. People look for the first time and realize either they've been covered well, or they've been so undercovered they aren't even on the policy.
If a mom reading this realizes she has no idea whether her coverage is actually right for her family or her business, what's the first thing she should do?
Find your declaration pages. For every policy you have, and anything you think you should have a policy for. Home, auto, RV, boat, wave runners, camper, trailer, your business, all of it.
Then look at them. If you don't understand what's being covered, what the liability covers, or what your deductible is, that's the moment to have a conversation. We do what I call a health checkup. We'll tell you if you're in a good place, if you need to make changes on your current policy, or if there's an opportunity to explore other carriers for a better product at a better price.
And yes, that includes pet insurance. We do everything but bail bonds. That's actually our tagline. Call my office and ask what we write, and any one of my staff will tell you: everything but bail bonds. Life insurance, retirement, long-term care, critical illness, you name it.
What makes working with a broker completely different from just buying a policy online or through an 800 number?
There's a reason we're licensed and required to have continuing education. We understand the market in a way the everyday buyer can't.
When you buy online or through an 800 number, you're typically working with one carrier, so you're only buying that carrier's product. As a broker, we represent multiple carriers. For our agency, that's a little over 60. Instead of cookie-cutting somebody into a policy, we tailor to what the client needs now, what they might need, and what they'll need in the future. As your life changes, we adjust how we protect you.
If someone's on the fence about whether they need to talk to you at all, what would you tell them?
An insurance check should be a yearly item on everybody's to-do list. If you're not currently working with somebody you feel has educated you and advocated for you, we're a local resource that understands the Bay Area and all of California, and we'd be glad to have that conversation. Whether that means confirming you're in good shape where you are, or exploring other options, the goal is the same. You sleep better at night.
And remember, everybody has too much insurance until the time of loss.
Email Joy at Joy@joyolivierinsurance.com
Call the office at 925-495-2244
CA Insurance License 0F05802
Find Joy Olivier on Facebook or connect and collaborate with her inside The Club membership for women Founders.